Dhaka 3:07 pm, Monday, 9 November 2026

Agriculture Loan Target Raised to Tk 60,000 Crore

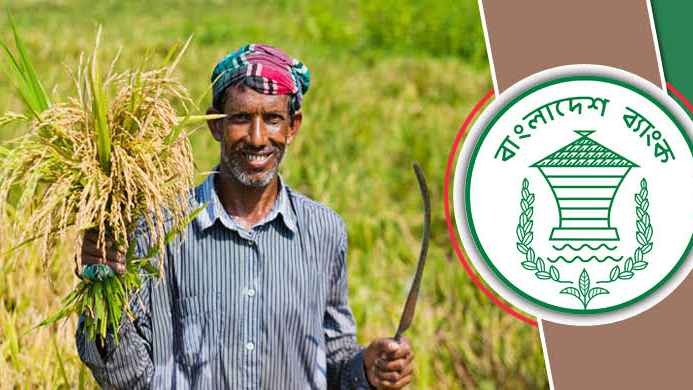
Bangladesh Bank has set a target of Tk 60,000 crore for disbursing agricultural and rural loans in the 2026-27 fiscal year to increase the flow of credit to the agriculture sector. The target is 53.8 percent, or Tk 21,000 crore, higher than the Tk 39,000 crore target set for the previous fiscal year. At the same time, banks have been instructed to strengthen monitoring to ensure that loans reach genuine and marginal farmers and are used for the intended purposes.

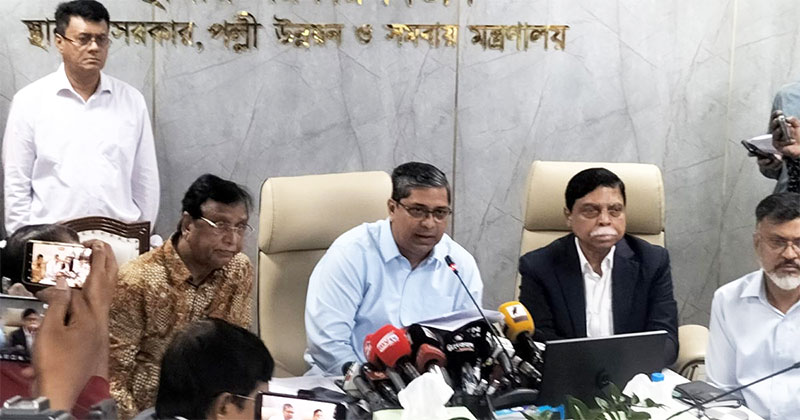
The information was disclosed at a programme held at Bangladesh Bank headquarters on Monday (August 17) to announce the Agricultural and Rural Credit Policy and Programme for the 2026-27 fiscal year. Bangladesh Bank Deputy Governor Dr Habibur Rahman highlighted the reasons behind the higher target and various aspects of the new policy.

Of the new target, Tk 20,845 crore has been allocated to state-owned commercial and specialised banks, while Tk 39,155 crore has been set aside for private and foreign commercial banks. This means the participation of private and foreign banks in agricultural lending is being further expanded.

Dr Habibur Rahman said the share of agricultural credit remains disproportionate compared with agriculture’s contribution to national income. As a result, the share of agricultural loans in total lending has been increased from 2.5 percent to 4 percent this year. There are plans to raise the share further in the future.

He said the main objective of increasing agricultural credit is to make agriculture self-reliant and empower farmers economically. The expansion of the volume and coverage of agricultural loans aims to enable farmers to become self-reliant through regular repayment rather than relying on loan waivers, increase production and play a greater role in the national economy.

Regarding the identification of genuine beneficiaries, the deputy governor said the two most important issues in agricultural lending are ensuring that loans reach genuine farmers and that they are delivered on time. If someone who is not a genuine farmer receives an agricultural loan, there is a risk that the money could be diverted to other sectors. Such misuse could also be viewed from the perspective of money laundering, he said.

He said providing loans to farmers holding Farmer Cards issued by the Department of Agricultural Extension is comparatively safer. However, if an applicant does not have a Farmer Card, the bank must verify whether the person is genuinely a farmer. Banks will have to bear responsibility if loans are disbursed without proper verification.

Responding to questions from journalists, Dr Habibur Rahman acknowledged allegations of middlemen and irregularities in agricultural loan disbursement. Bangladesh Bank regularly conducts surveys and monitoring to determine whether loans are reaching genuine farmers and whether the funds are being used properly. He assured that monitoring would be strengthened further.

Questions were also raised about the practice of adjusting previous loans and providing new loans by Bangladesh Krishi Bank and Rajshahi Krishi Unnayan Bank. In response, Dr Habibur Rahman said the practice cannot be viewed negatively in every case. If a farmer repays a previous loan and receives a higher amount based on their needs and repayment capacity, it may be considered an expansion of new lending. However, repeatedly renewing the same loan for a long period without assessing the farmer’s actual needs should be brought under control.

He said the most important issue after a loan is disbursed is whether the money is being used for the proper purpose. Banks must also assess whether farmers have developed the capacity to repay loans by investing the funds in productive activities. The use of loan funds and repayment capacity must be monitored from the very beginning of the lending process.

The new policy places emphasis on distributing loans based on the type of agriculture and demand in different regions. Banks have been instructed to follow an “area approach” in this regard. For agricultural lending, banks will be able to use the Bangladesh government’s Crop Zoning information, the Khamari app, and data from the Bangladesh Bureau of Statistics, Department of Agricultural Extension and Department of Fisheries. They have also been advised to use crop zoning data from the Bangladesh Agricultural Research Council to determine region-specific agricultural production and credit demand.

Dr Habibur Rahman said loan targets should be determined according to the dominant agricultural activities in each area—whether rice, potatoes, fish or other agricultural products. Loan limits have been determined based on production volume, land area, fertiliser, seeds, labour and other production costs. However, if market prices are not aligned with production costs, the loan limits may be increased or reduced according to need.

The new policy expands opportunities for collateral-free loans and alternative forms of collateral for women and marginal farmers. Lending has also been expanded to the fisheries and livestock sectors. For loan applications of up to Tk 5 lakh, banks have been instructed not to accept charge documents other than certain specified documents.

The policy also places emphasis on allowing personal, social and group guarantees instead of conventional land or immovable property as collateral when providing loans to women and marginal farmers.

The policy stresses ensuring that agricultural loans are used only for the designated sectors. Banks will be able to provide loans to individual or groups of farmers and livestock or fishery entrepreneurs. Various activities, including poultry chick production, hatcheries and fish fry production, have been brought under the lending programme.

The policy also gives importance to addressing the impacts of climate change, contract farming, production of new crops and post-harvest management of agricultural products.

The new programme also incorporates summaries of policies related to a Tk 10,000 crore refinancing scheme and a Tk 3,000 crore refinancing fund. Various opportunities are being expanded to bring small-capital farmers, new entrepreneurs and specific production sectors under the credit programme.

The deputy governor said the agricultural and rural credit target had been increased by Tk 21,000 crore from the previous year to Tk 60,000 crore. However, the objective is not merely to increase the volume of loans, but also to ensure that credit reaches genuine farmers and is used for productive purposes. Greater emphasis is being placed on enabling farmers to increase production through borrowing and build the capacity to obtain larger loans in the future by repaying their loans on time.

He further said banks had been instructed to ensure that there are no irregularities or deviations in agricultural loan disbursement. Bangladesh Bank’s own teams will also monitor the entire process. The central bank will strengthen its oversight to ensure the identification of genuine farmers, proper use of loan funds and timely disbursement of agricultural credit.
Agriculture Loan Target Raised to Tk 60,000 Crore

Update Time: 06:30:11 pm, Monday, 17 August 2026

Bangladesh Bank has set a target of Tk 60,000 crore for disbursing agricultural and rural loans in the 2026-27 fiscal year to increase the flow of credit to the agriculture sector. The target is 53.8 percent, or Tk 21,000 crore, higher than the Tk 39,000 crore target set for the previous fiscal year. At the same time, banks have been instructed to strengthen monitoring to ensure that loans reach genuine and marginal farmers and are used for the intended purposes.

The information was disclosed at a programme held at Bangladesh Bank headquarters on Monday (August 17) to announce the Agricultural and Rural Credit Policy and Programme for the 2026-27 fiscal year. Bangladesh Bank Deputy Governor Dr Habibur Rahman highlighted the reasons behind the higher target and various aspects of the new policy.

Of the new target, Tk 20,845 crore has been allocated to state-owned commercial and specialised banks, while Tk 39,155 crore has been set aside for private and foreign commercial banks. This means the participation of private and foreign banks in agricultural lending is being further expanded.

Dr Habibur Rahman said the share of agricultural credit remains disproportionate compared with agriculture’s contribution to national income. As a result, the share of agricultural loans in total lending has been increased from 2.5 percent to 4 percent this year. There are plans to raise the share further in the future.

He said the main objective of increasing agricultural credit is to make agriculture self-reliant and empower farmers economically. The expansion of the volume and coverage of agricultural loans aims to enable farmers to become self-reliant through regular repayment rather than relying on loan waivers, increase production and play a greater role in the national economy.

Regarding the identification of genuine beneficiaries, the deputy governor said the two most important issues in agricultural lending are ensuring that loans reach genuine farmers and that they are delivered on time. If someone who is not a genuine farmer receives an agricultural loan, there is a risk that the money could be diverted to other sectors. Such misuse could also be viewed from the perspective of money laundering, he said.

He said providing loans to farmers holding Farmer Cards issued by the Department of Agricultural Extension is comparatively safer. However, if an applicant does not have a Farmer Card, the bank must verify whether the person is genuinely a farmer. Banks will have to bear responsibility if loans are disbursed without proper verification.

Responding to questions from journalists, Dr Habibur Rahman acknowledged allegations of middlemen and irregularities in agricultural loan disbursement. Bangladesh Bank regularly conducts surveys and monitoring to determine whether loans are reaching genuine farmers and whether the funds are being used properly. He assured that monitoring would be strengthened further.

Questions were also raised about the practice of adjusting previous loans and providing new loans by Bangladesh Krishi Bank and Rajshahi Krishi Unnayan Bank. In response, Dr Habibur Rahman said the practice cannot be viewed negatively in every case. If a farmer repays a previous loan and receives a higher amount based on their needs and repayment capacity, it may be considered an expansion of new lending. However, repeatedly renewing the same loan for a long period without assessing the farmer’s actual needs should be brought under control.

He said the most important issue after a loan is disbursed is whether the money is being used for the proper purpose. Banks must also assess whether farmers have developed the capacity to repay loans by investing the funds in productive activities. The use of loan funds and repayment capacity must be monitored from the very beginning of the lending process.

The new policy places emphasis on distributing loans based on the type of agriculture and demand in different regions. Banks have been instructed to follow an “area approach” in this regard. For agricultural lending, banks will be able to use the Bangladesh government’s Crop Zoning information, the Khamari app, and data from the Bangladesh Bureau of Statistics, Department of Agricultural Extension and Department of Fisheries. They have also been advised to use crop zoning data from the Bangladesh Agricultural Research Council to determine region-specific agricultural production and credit demand.

Dr Habibur Rahman said loan targets should be determined according to the dominant agricultural activities in each area—whether rice, potatoes, fish or other agricultural products. Loan limits have been determined based on production volume, land area, fertiliser, seeds, labour and other production costs. However, if market prices are not aligned with production costs, the loan limits may be increased or reduced according to need.

The new policy expands opportunities for collateral-free loans and alternative forms of collateral for women and marginal farmers. Lending has also been expanded to the fisheries and livestock sectors. For loan applications of up to Tk 5 lakh, banks have been instructed not to accept charge documents other than certain specified documents.

The policy also places emphasis on allowing personal, social and group guarantees instead of conventional land or immovable property as collateral when providing loans to women and marginal farmers.

The policy stresses ensuring that agricultural loans are used only for the designated sectors. Banks will be able to provide loans to individual or groups of farmers and livestock or fishery entrepreneurs. Various activities, including poultry chick production, hatcheries and fish fry production, have been brought under the lending programme.

The policy also gives importance to addressing the impacts of climate change, contract farming, production of new crops and post-harvest management of agricultural products.

The new programme also incorporates summaries of policies related to a Tk 10,000 crore refinancing scheme and a Tk 3,000 crore refinancing fund. Various opportunities are being expanded to bring small-capital farmers, new entrepreneurs and specific production sectors under the credit programme.

The deputy governor said the agricultural and rural credit target had been increased by Tk 21,000 crore from the previous year to Tk 60,000 crore. However, the objective is not merely to increase the volume of loans, but also to ensure that credit reaches genuine farmers and is used for productive purposes. Greater emphasis is being placed on enabling farmers to increase production through borrowing and build the capacity to obtain larger loans in the future by repaying their loans on time.

He further said banks had been instructed to ensure that there are no irregularities or deviations in agricultural loan disbursement. Bangladesh Bank’s own teams will also monitor the entire process. The central bank will strengthen its oversight to ensure the identification of genuine farmers, proper use of loan funds and timely disbursement of agricultural credit.